
In Cornerstone Advisors’ 2026 What’s Going On in Banking report, I equated bankers in 2026 to Dorothy and her Wizard of Oz pals heading into the woods, arm in arm, chanting “AI, crypto, and fraud, oh my.”
The study found that going into 2026, financial institution execs were:
Optimistic. Credit union execs more so than bankers.
Growth-focused. New customer growth jumped to the top of the concern list.
Deep into AI. Gen AI deployment among credit unions hit 59%. Agentic AI: 17%.
Talking tokenization. On the agenda at 71% of boards, but 0% deployment.
Halfway through the year, nobody’s been eaten. But the trees look different than they did at the beginning of the year, and a few things came crashing out of the underbrush that nobody had anticipated in January.
What did bankers spend the first half of 2026 learning that they didn’t expect to learn?
Competition changed faster than expected (fintechs, checking, Bizumers).
Technology changed faster than expected (AI plumbing, agentOS, Plaid, Anthropic).
Distribution didn’t change the way people think (the Chase branch myth).
Money is becoming more mobile than banks assume (deposit mobility, tokenization, stablecoins).
The economy didn't collapse, but it didn't provide much help either. Growth softened, confidence weakened, and uncertainty stayed elevated.
My take: The banking industry spent the first half of 2026 adapting to structural shifts that had little to do with GDP or interest rates: fintechs kept taking checking and payment account share, AI infrastructure accelerated, and the assumptions underlying deposit strategy continued to erode.
Fintechs Ate the Checking Account
Big fintechs—PayPal, Block—hit 80% on the “significant threat” list going into 2026, up from 47% three years ago. Challenger banks like Chime posted the biggest jump of the group, from 21% to 70%. Crypto providers entered the chart at 29%.
The fear is well-founded: Fintechs opened 56% of new checking and payments accounts in 2025, up from 36% in 2020. Megabanks fell from 24% to 13% over the same stretch. Credit unions and community banks are mired in single digit market share.
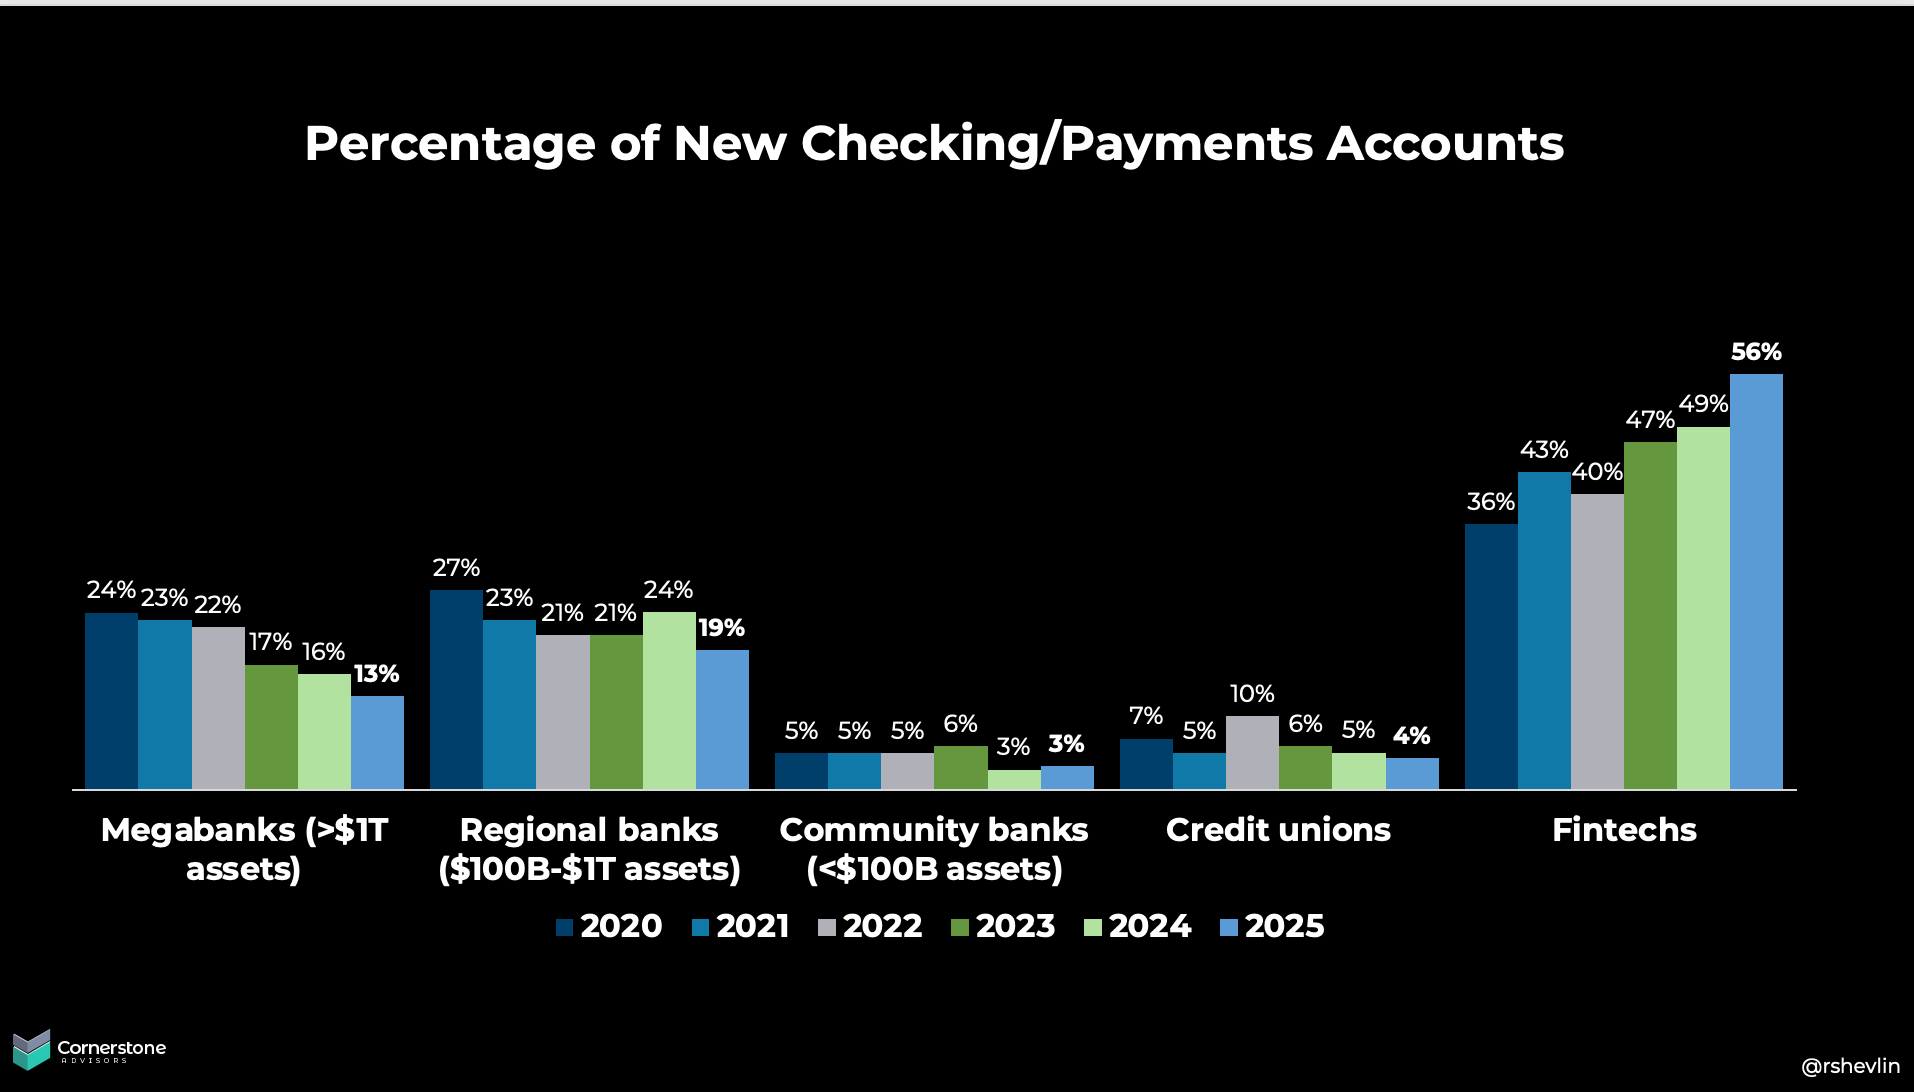
Who’s doing the damage: PayPal (16% of new accounts), Chime (10%), Venmo (10%), with SoFi and Cash App climbing through the 5-6% range.
Why this is happening: This is a product-market fit story. Fintechs are winning because they're designing accounts around the financial lives people lead—digital-first, multi-provider, increasingly entrepreneurial, and less loyal to a single institution.
AI: The Battle Lines are Getting Clearer
The first half of 2026 produced some important AI infrastructure announcements. Plaid launched a financial foundation model. FIS partnered with Anthropic. Fiserv introduced agentOS. These weren’t announcements about better chatbots. They were announcements about who intends to own the operating system for banking AI.
These moves change the face of the vendor landscape in banking:
Plaid expands more broadly into credit underwriting and scoring, offering a(nother) legitimate alternative to FICO.
The big 3 cores take on big AI lab partners providing access—albeit not very direct access—that their client base could never get on their own.
But here’s what’s getting lost in all the excitement over Claude, ChatGPT, Gemini, and Llama: the strategic battle is over the orchestration layer.
Vendors love to talk about “model neutrality.” It’s become the AI equivalent of “open architecture.”
But model neutrality is just marketing until it’s written into the contract. The vendor that controls how AI agents authenticate, retrieve data, invoke systems, and hand work off to other agents owns the customer relationship regardless of which foundation model happens to sit underneath.
Banks think they're selecting AI models. In reality, they're selecting the platform that will determine which models they can use, how easily they can change them, and who captures the value created by AI.
As foundation models commoditize, competitive advantage shifts upward. The model becomes a component, not the product. The orchestration layer—the software that decides which model to call, when to call it, what context to provide, and what actions to take—becomes the strategic control point.
It’s Not About Stablecoins, It’s About Deposit Mobility
NO—ChatGPT did not write that headline for me.
The GENIUS and CLARITY Acts moved the conversation from whether digital dollars belong in the financial system to how they’ll operate. But bankers are asking the wrong question.
The biggest strategic mistake banks can make is thinking the issue is stablecoins. It isn’t. The issue is deposit mobility.
The concept of “core deposits” no longer holds. There are no core deposits. They’re all movable. That trend didn’t start with stablecoins, and it won’t end with them. Stablecoins simply accelerate a shift that’s already underway.
The question banks need to answer: “What happens when deposits become dramatically more mobile?” Today’s deposits are surprisingly sticky. Payroll lands every two weeks. Bill pay follows predictable cycles. Moving money between institutions takes enough time and friction that inertia works in banks’ favor.
Programmable digital dollars change that equation. Money that can move 24/7, settle in seconds, and be embedded directly into software becomes easier to redirect.
Treasury systems, AI agents, and business applications won’t care whether value moves via ACH, RTP, FedNow, tokenized deposits, or regulated stablecoins. They’ll choose whatever rail is fastest, cheapest, or built into the workflow. That’s the issue.
Stop managing deposits as if inertia is a strategy. For decades, friction was one of banking's most profitable products. Deposits stayed because moving them wasn't worth the effort. Programmable money eliminates the friction.
Branches Aren’t Dead (Yet)
Conventional wisdom: branches are back, and Chase is proof.
Reality: Chase is proving that Chase can make branches work. Marianne Lake, who ran Chase’s consumer and community bank, said:
“Increasing branches is directly correlated with deposit growth, with new branches accounting for 40% of JPMorgan Chase’s new deposit share gains.”
That stat has been mangled by the trade press and quoted as 40% of its deposits or 40% of its deposit growth. That’s not what she said.
Chase's own data tells a different story.
Back in 2021 it said that half of its new consumer accounts were opened digitally, and that number hasn’t gone backward. But its share of new retail checking accounts fell from 5.2% to 3.7% in a single year.
The buildout is about small business relationships, wealth deepening, and planting a flag in markets Chase didn’t serve: relationship managers on the ground, referrals from accountants and attorneys, advisors chasing affluent households. It’s a real strategy with real ROI—for Chase.
The question for smaller financial institutions: is your distribution strategy focused on winnable customers? Even Chase’s small business bet rests on an assumption that Brex, Ramp, and Mercury are working to invalidate.
The Rise of the Bizumer
The classic W‑2 consumer—one employer, steady paycheck, predictable cash flow—is no longer the dominant growth customer.
Today’s young consumers are Bizumers—half consumer, half small business. Personal and business cash flows blur. Credit needs straddle consumer and business products. The bureau file wasn’t built for these people. Nor are traditional checking accounts.
The Fed pegs roughly 32 million American adults as effectively un-scoreable. For plenty of them, the signal is sitting right there in the file. The models just don’t go looking, because they’ve barely changed in how they read the data they already have.
Fix the model and a big, underserved, entrepreneurial market snaps into focus. SoFi’s push into small business lending is a bet on that market.
Prebuilding the Future
The first half of 2026 was when long-building trends became impossible to ignore. If there’s one word worth using going into 2027 strategy conversations, it’s prebuilding.
Two quotes make the case:
“The risk of under-investing is significantly greater than the risk of over-investing.” (Sundar Pichai, 2024)
“The very worst case would be that we have just prebuilt for a couple of years.” (Mark Zuckerberg, 2025)
Prebuilding means laying track before the train shows up: the data infrastructure, the governance, and the experiments that tell you what’s possible before you commit real money. Five places to start prebuilding:
AI. Management owns three questions: 1) how does AI change how people work? 2) how does it change who does the work? and 3) How fast can you get—at what rate of change, at what cost, and at what level of operational risk?
Data. Grade your data quality function by function, put the functional heads on the hook for the score, and get it AI-ready. It’s unglamorous, and it gates everything else on this list.
Governance. What’s missing: an AI deployment policy that controls how AI systems run in the tech environment, who built them, how they’re tested, and what they do with data.
Tokenization. Questions to address: 1) what happens ALM models when money can leave the balance sheet 24/7 with minimal friction; 2) what’s the case for stablecoin payments/cash management; and 3) who builds the digital asset stack?
Products. Banking products are evolving from informational to active and autonomous, fueled by AI agents. Which market segments offer growth opportunities, and what products will meet the needs of those segments?
Get Up Offa That Thing
So where does this midpoint leave you? The winners will react, adjust, and prebuild. The losers will play “wait and see.” James Brown nailed it 50 years ago when he sang “get up offa that thing.” Whatever you do for the rest of 2026, don’t do nothing.